Argentina's Critical Minerals Strategy: Opportunities and Challenges Ahead
Published Sep 12, 2026Reads 614By Jennifer Heiman & Eric Kenny
Argentina aims to capitalize on its lithium and copper resources but risks dependency on raw exports without building local processing capabilities.
The Stakes of Argentina's Critical-Minerals Push
Argentina finds itself at a pivotal moment in its quest for prosperity within the critical minerals sector. The recent influx of investments, particularly in lithium and copper, has sparked widespread attention. But the questions that loom large are about the country's strategic choices moving forward.
On July 31, 2026, Argentina signed a landmark partnership with South Korea aimed at harnessing the entire lithium value chain. Furthermore, the government approved Posco’s expansion of lithium-carbonate production at the Salar del Hombre Muerto specifically for export. This aggressive push comes amid global supply chain shifts and an urgent U.S. need to establish less China-dependent pathways for critical minerals. With the Régimen de Incentivo para Grandes Inversiones (RIGI) scheme in motion, the opportunities for Argentina to reshape not only its economic status but also its geopolitical role in the critical minerals landscape are noteworthy.
President Javier Milei's administration seems to recognize the significance of the moment. With investments pouring in and lucrative deals beckoning, the swift implementation of RIGI reflects a strategy designed to capitalize on the current high demand for critical minerals. The real question, however, is what Argentina envisions for itself in this evolving supply chain.
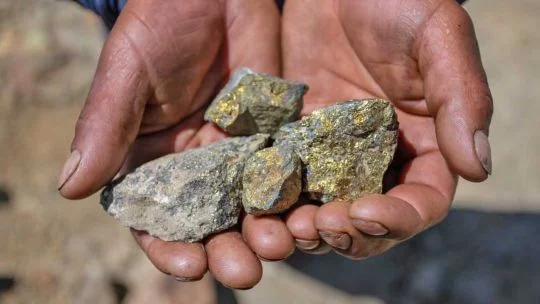
If you're exploring this space, it's critical to note that the dominant focus thus far has been on extracting raw materials. This familiar trajectory offers immediate financial returns, but passing up the chance to develop robust domestic processing capabilities could trap Argentina in a cycle of raw-export dependency. The economic risks inherent in such a scenario are evident, as global market fluctuations could dictate the nation's fortunes.
Refining Decisions
Despite Argentina's rich deposits of lithium and copper, the country lacks substantial refining capacity, leaving it vulnerable to the whims of international markets. China currently controls a dominant share of the global lithium refining sector, which complicates Argentina's position as it ramps up production. Should Argentina choose to remain chiefly an exporter of raw materials, it risks falling victim to global commodity price swings similar to those faced in its agricultural sector.
Ambition exists, albeit in limited form. Progress has been made with initiatives like YPF’s pilot lithium-cell plant, which, while a promising step, remains far from a full-fledged industrial program. The government's current inclination toward traditional oil and gas sectors has stalled the development of battery manufacturing, underscoring a disconnect between ambitious rhetoric and actionable progress.
Emerging from this dilemma is Argentina's historical relationship with its agricultural exports, particularly soy. The country has achieved success in this domain by investing in domestic crushing facilities rather than simply shipping raw crops. While lithium isn't soy, looking to replicate this pattern could provide a pathway for increasing domestic value addition in the critical minerals sector.
However, the challenges shouldn’t be understated. Lithium processing involves complex technology and significant capital investment. Failing to navigate these hurdles could mirror Indonesia’s experience, where a ban on raw nickel exports catalyzed domestic processing growth but at the cost of foreign control over the industry.
If approached wisely, the shift towards local processing could catalyze job creation and build essential local competencies. Argentina's economy has lost a considerable number of jobs since the beginning of Milei's administration, highlighting an urgent need for strategies that foster sustainable growth. With the RIGI scheme's application period extending until July 2027, a strategic shift now could bear long-term benefits for the nation’s economy, regardless of political changes in the upcoming elections.
Local Engagement and Risks
A significant portion of the political and operational risks linked to Argentina's mining ambitions arises from the provinces hosting these projects. With major lithium and copper endeavors largely concentrated in regions like Jujuy, Salta, and Catamarca, the success of these projects hinges on the local communities' willingness to embrace them. Building effective governance and regulatory coordination at a provincial level will be critical in fostering the social licenses necessary for these initiatives to thrive.
Experts point to the necessity of forging a strong social contract—one that aligns community interests with the economic benefits of mining. Water scarcity poses a particularly pressing issue, as lithium extraction relies on aquifers in arid regions. Local stakeholders must assess whether the perceived benefits of mining justify the potential ecological impacts they might face.
Interestingly, developing local processing capabilities could enhance community support. Instead of merely observing raw materials leave their regions, communities would gain from the presence of processing plants that create jobs and generate tax revenue. While provincial authority can facilitate local engagement, it can also complicate and delay projects if bureaucratic inefficiencies arise.
Comparatively, Indonesia’s approach to domestic processing offers valuable lessons. As it developed its nickel industry, the reliance on foreign investments prompted complications related to environmental governance.
In conclusion, as Argentina navigates the complexities of its critical minerals surge, the choices it makes now will determine whether it becomes a key player in global supply chains or remains a peripheral exporter. The country stands at a crossroads; the path forward promises both opportunities and significant demands for strategic foresight.
Future Legislation and External Pressures
Investor sentiments toward Argentina have evolved over time, with currency volatility historically raising red flags. The RIGI framework aims to mitigate this risk by promising stable access to foreign currency for registered projects, a move meant to facilitate large-scale investments.
Yet, questions linger about the longevity of these guarantees. The proposed Super RIGI scheme aims to extend investment security for mega-projects, but the regulatory landscape needs careful navigation if Argentina is to develop a sustained cathode or battery industry. Any delays in implementing necessary legislation could result in missed opportunities, stalling the momentum that's been built up.
In contrast, neighboring Chile has actively shaped its lithium narrative by prioritizing domestic processing and regulatory frameworks designed to empower state control. Their approach, while slower, emphasizes a long-term strategy that Argentina might find worthwhile to study.
In short, while Argentina holds substantial leverage in this critical minerals arena, it needs to avoid overselling its position. Resource-rich nations have historically struggled to capture significant value from their exports. The timing for Argentina is unique, and whether it can transform this moment into lasting economic prosperity hinges on decisive action and well-defined policies. The industry awaits the outcome of these choices, with the international gaze firmly fixed on the region.
Discussion
Sign in to join the discussion.